 Manchester Sourcing
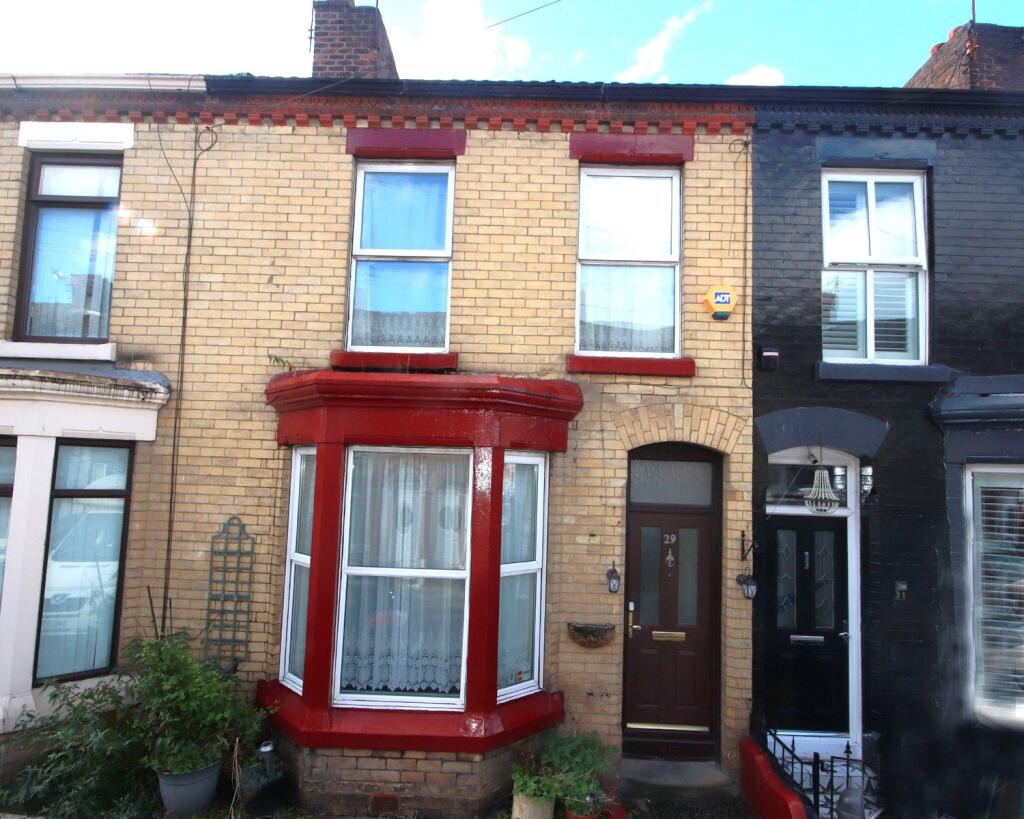
29 Euston Street, Liverpool, L4 5PR
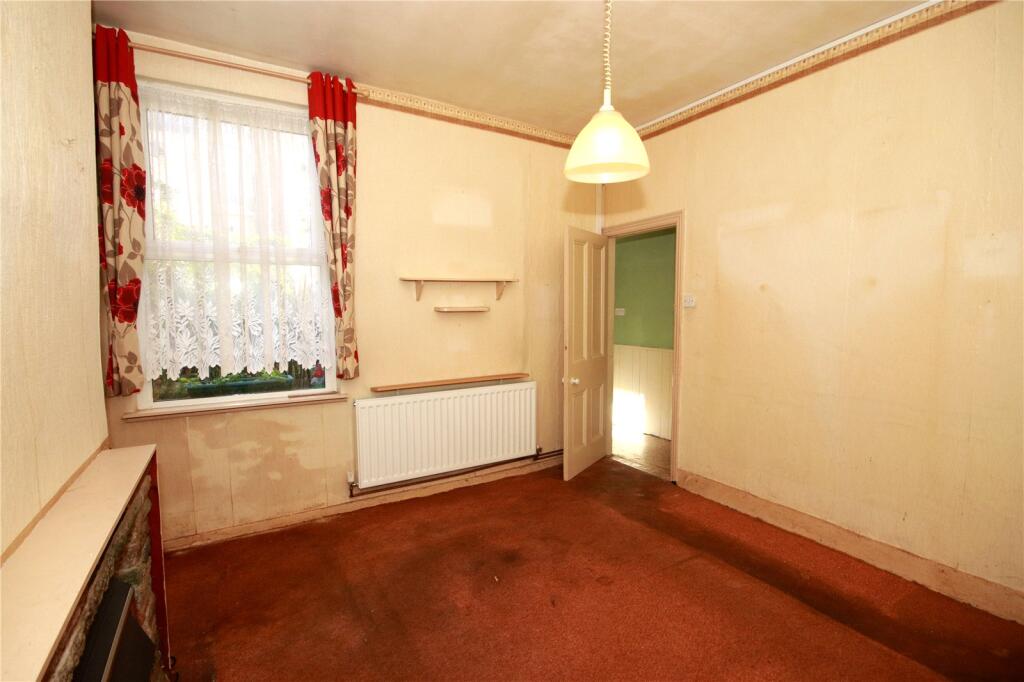
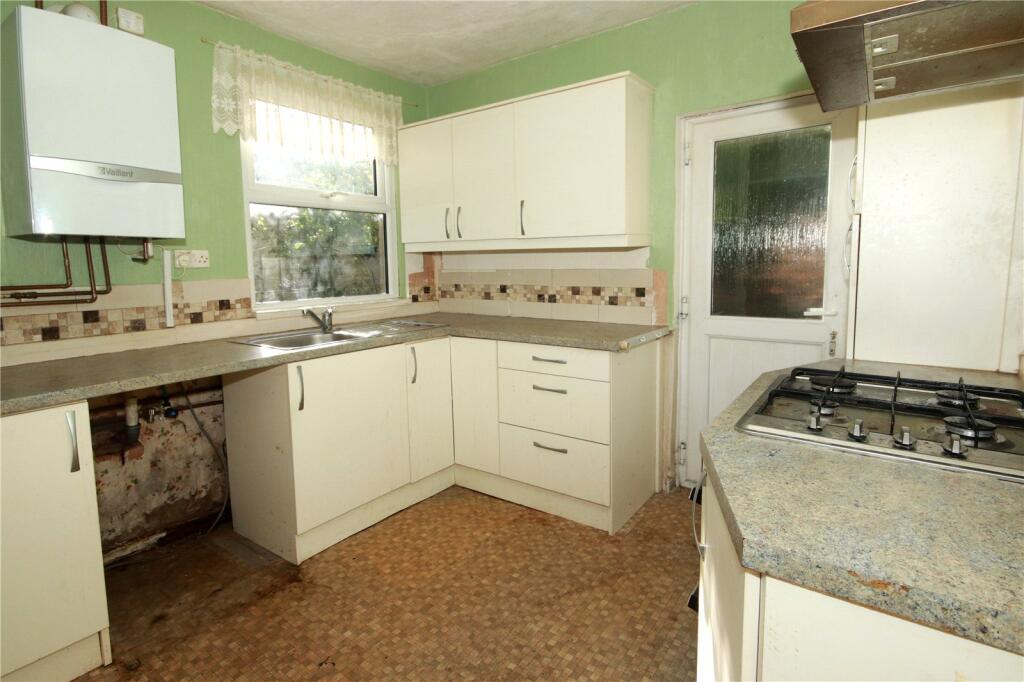
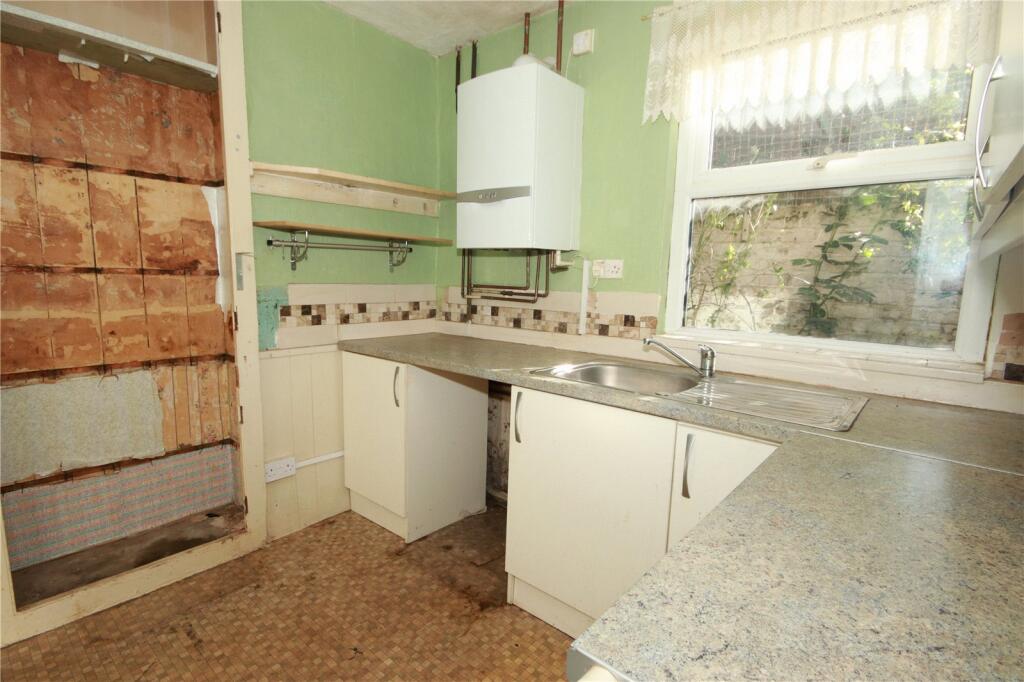
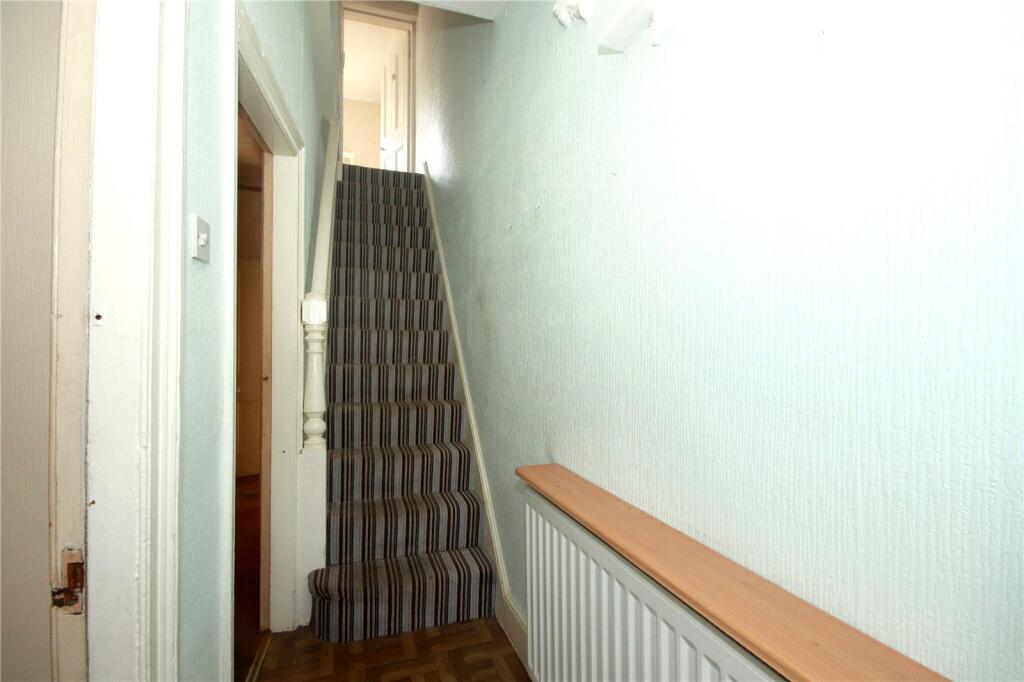
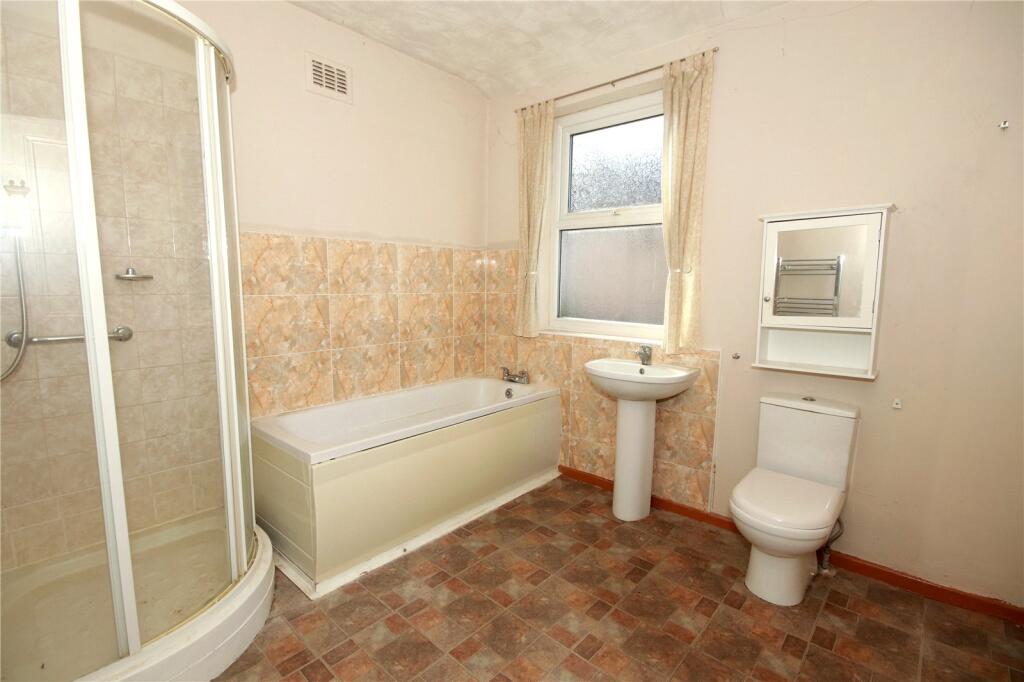
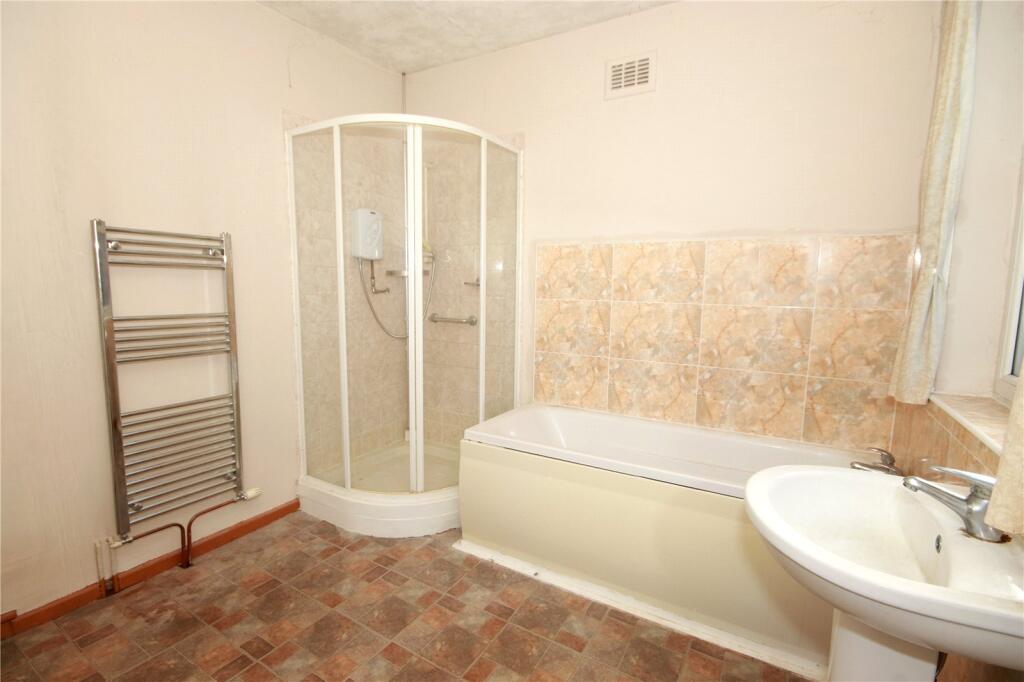
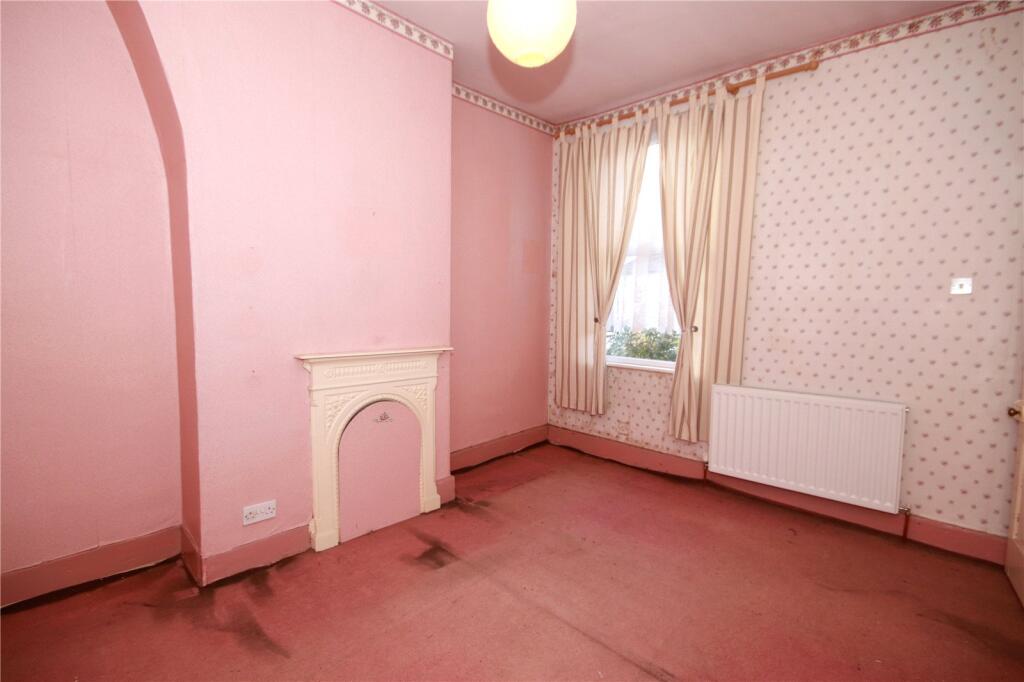
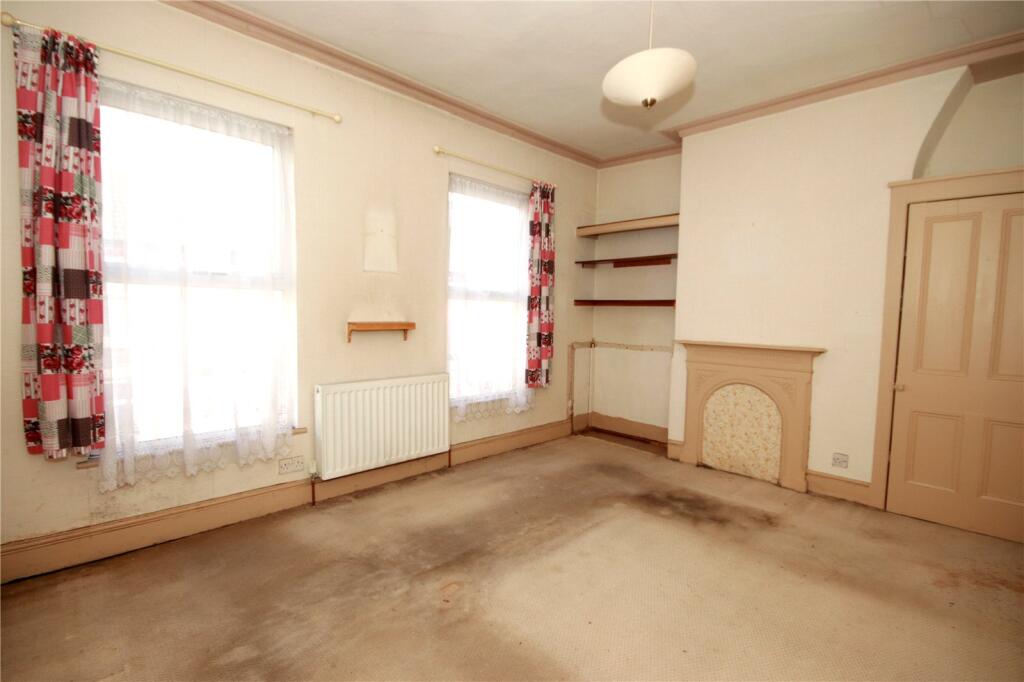
2 bedroom house, to be fully refurbished before handover, on 29 Euston Street, Liverpool, L4 5PR.
To be let on a 3-year lease with an established social housing provider at £800 pcm (£9,600 per annum). The provider takes the whole property, so the landlord is not managing individual tenancies.
Purchase £90,000, refurbishment £10,000 + VAT. Yield 9.41% on the purchase price plus the refurbishment.
Euston Street is in Walton, L4, north Liverpool, a street of Victorian terraced houses off County Road, about three miles from the city centre, with the County Road shops, schools and bus routes into town close by. Council tax band A, flood risk very low.
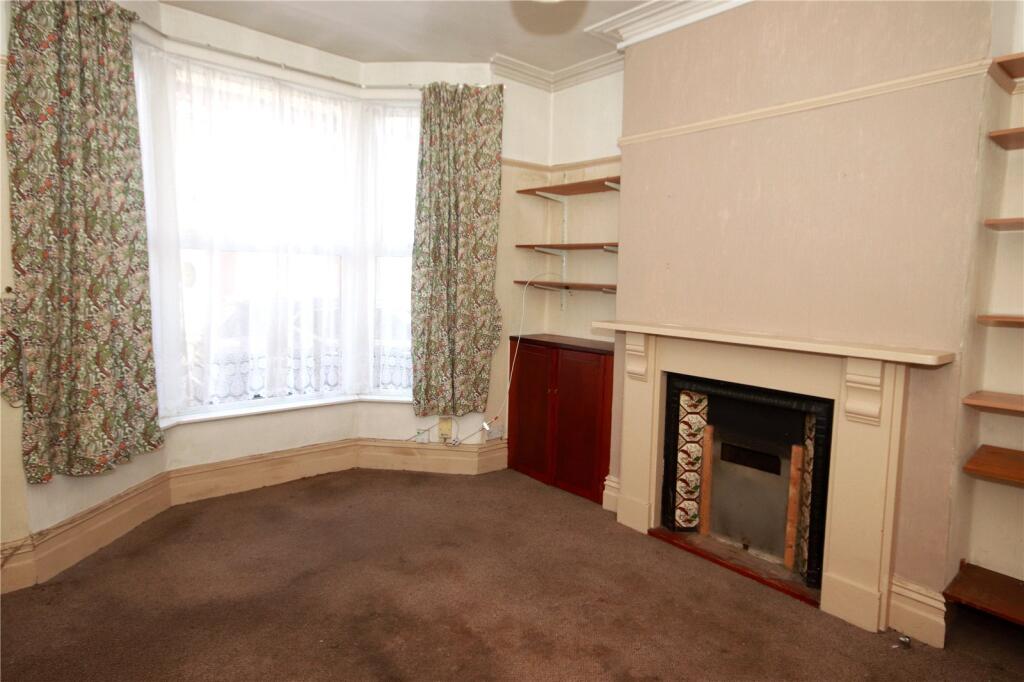
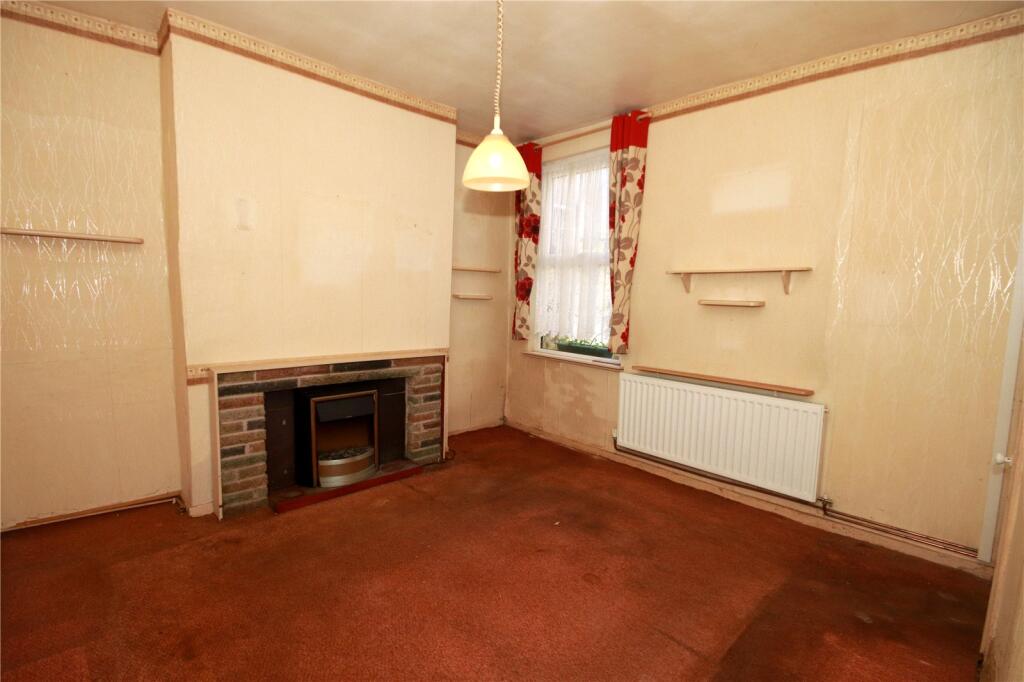
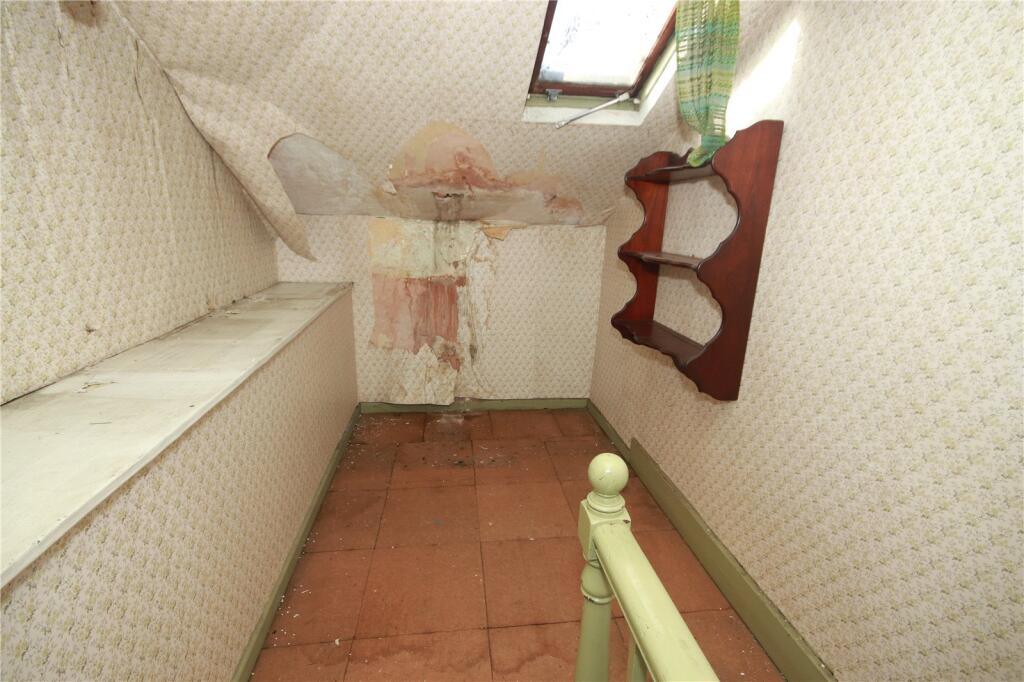
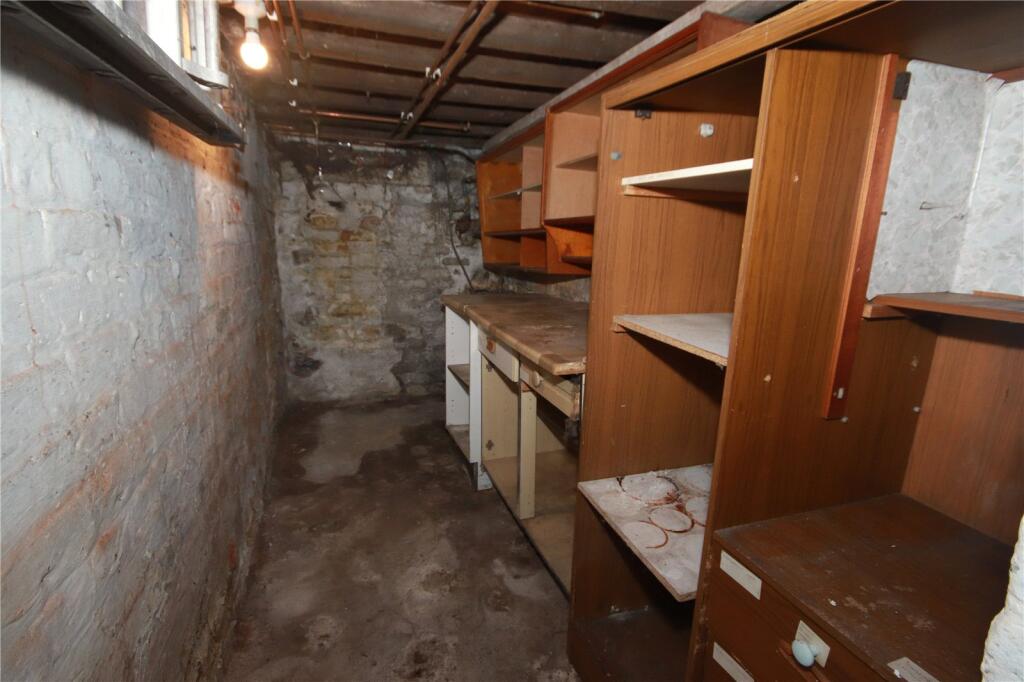
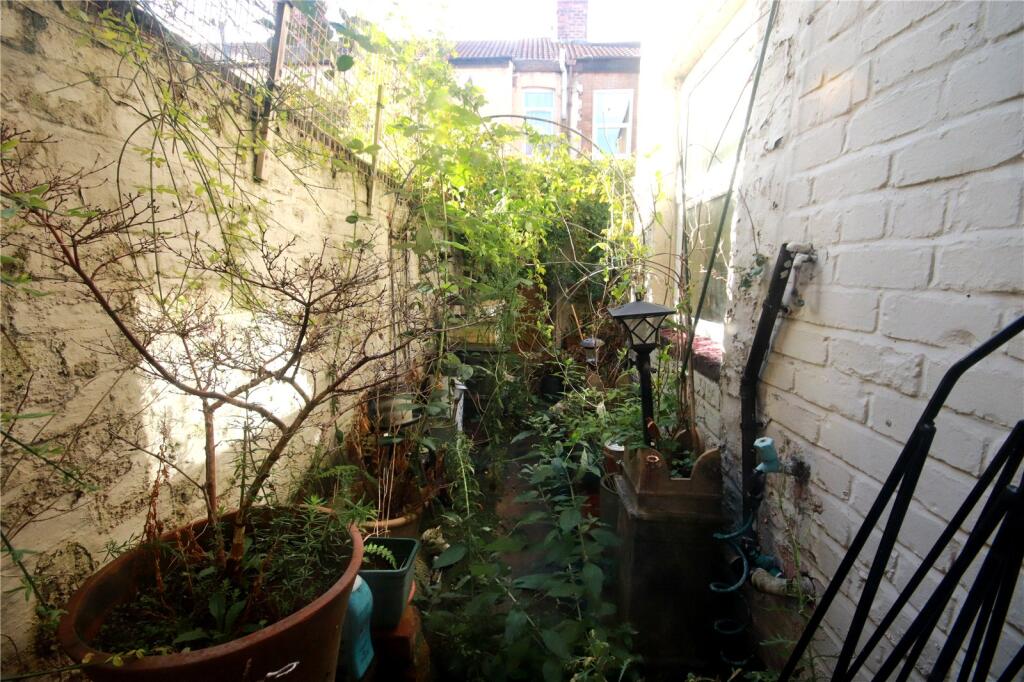
The house is two bedrooms with a loft room and a basement. The work is carpets, decoration, updating the bathroom and kitchen, damp treatment, a roof repair and clearing the garden: £10,000 + VAT in total.
Stamp Duty, legal fees and other acquisition costs are not included and depend on the purchaser's circumstances. Figures are indicative and should be verified before exchange.
The lease
The lease is with the provider, not the tenant. The rent arrives whether the house is full or empty.
Where it goes onto a provider lease, the house is let to a family on a single lease, not by the room.
They cover the tenancies, the utilities, the council tax and any tenant damage.
You cover the exterior, the electrics, the boiler and the pipework. Boiler cover runs about £15–20 a month and takes the worst of that off the table.
Refurbishment
New carpets, painting, bathroom and kitchen updating, damp treatment, roof repair, garden clearance and project management.
Video walkthrough
What you put in, and what comes back.
The same house is a different deal depending on where you pay tax, so both are set out. Stamp duty and the mortgage rate are the two things that change.
Buying from overseas
interest-only at 75% loan to value, fixed for 5 years, through a specialist lender that funds overseas investors on social housing leases. Stamp duty at the additional-property rate plus the non-resident surcharge.
Buying as a UK investor
interest-only at 75% loan to value, through a mainstream buy-to-let lender. Stamp duty at the additional-property rate.
An illustration, not a quote and not an offer of finance. The overseas figures reflect a product we have placed repeatedly; the UK rate is indicative of mainstream buy-to-let lending. Rates, lending criteria and the deposit a lender asks for all move — take your rate from a broker, not from a website. Stamp duty is England and Northern Ireland, at the additional-property rate because every purchase here is an additional property; "non-resident" is a statutory test, not nationality, and your solicitor confirms the figure and files the return. Rates change at Budgets (these are the rates from 2 April 2026). Legal and purchase costs are an allowance covering legals, survey and insurance, not a quote. Net income is after mortgage interest and before maintenance and voids, insurance, your own tax, and management where a property is not on a provider lease.
Why we buy in Liverpool.
Liverpool is our home market and has been from the start. The great majority of what we have bought sits in the north and east of the city — Anfield, Kirkdale, Everton, Walton, Kensington, Edge Hill, Old Swan and Tuebrook.
Want the numbers behind this one?
We'll send the comparable evidence, the refurbishment schedule and the rental assessment. If they don't stand up, don't buy it.